Maximizing Profitability Through Strategic Reinsurance
Thought and preparation should be leveraged in deciding how your dealership applies this wealth-generating tool.

It’s essential to recognize that not all products are suitable for inclusion in reinsurance programs.
Pexels/Artem Podrez
Navigating the complexities of reinsurance and wealth management can be overwhelming, especially when your primary focus as a dealer is ensuring that your F&I products align with your financial objectives. The decisions you make regarding these products directly influence the strength and sustainability of your reinsurance program. Now might be the right time to reassess your current structure and determine if you’re truly maximizing your profitability and wealth-building potential.
The Strategic Advantage of Reinsurance
Reinsurance programs offer a unique opportunity to enhance wealth by allowing dealers to retain a significant portion of the profits generated from F&I products. However, while the benefits are clear, not all reinsurance platforms are created equal. The automotive industry has evolved, with increased regulations providing greater stability, but understanding the available options is critical to selecting the right fit for your dealership.
Tailored Solutions for Optimal Results
Each dealership has distinct needs. The key to success is selecting the right structure and products that not only appeal to your customers but also contribute to profitability. Wealth management in this space involves partnering with financial experts who are well-versed in reinsurance intricacies. These partners should align with your goals and help steer your program toward maximum returns—a factor that is often overlooked but crucial to long-term success.
For instance, retrocession, or retro, reinsurance is an option that transfers the risk to another reinsurer. While this platform offers profit participation without exposure to losses, it has limitations. Dealers benefit only if losses remain below 100%, and there’s no opportunity for investment income. Additionally, the administrator handles claims, limiting control. For smaller dealerships, a retro program can be a viable option, particularly for service contracts, provided they meet the minimum annual qualifications.
Alternatively, dealer reinsurance allows dealers to share in the underwriting profits from F&I products sold. This option demands diligence, particularly in understanding the varying administration fees associated with different service contracts. Ensuring you receive equitable service for the fees charged is crucial for maintaining profitability.
Enhancing Customer Loyalty and Retention
Relying on OEM factory contracts may seem like a safe option, but it offers little in terms of customer loyalty or service retention. These contracts often do little to drive repeat business, handing your clients back to the OEM and missing the chance to build long-term relationships. Incorporating customer retention and loyalty into your reinsurance strategy can set your dealership apart and strengthen your reputation.
Maximizing Reinsurance Success
It’s essential to recognize that not all products are suitable for inclusion in reinsurance programs. Certain high-end models may not fit, and direct deals might offer better outcomes. Understanding the various fees associated with reinsurance—administration fees, ceding fees, premium taxes, and repair order fees—is critical. Working with experienced F&I agents can provide valuable insights, including potential discounts on admin fees and enhanced dealer support.
Regularly reviewing your cession statements—typically released quarterly—is a best practice. These statements offer crucial insights into claims paid and the overall health of your reinsurance company. A typical benchmark is a 60%-profit-to-40%-loss ratio, but staying informed is essential for maintaining a profitable reinsurance program.
Regular Reinsurance Check-Ups: The 18-Month Rule
Dealers should aim to reassess their reinsurance structures every 18 months to ensure profitability and efficiency. Keeping an eye on losses, adjusting premiums accordingly, and ensuring no additional fees are creeping into your admin charges are key steps to maintaining profitability.
Which Products Should Be Included?
Certain products perform better under reinsurance, particularly on nonhighline vehicles. These include:
Service contracts
Tire-and-wheel protection
Chemicals
Etch
Prepaid maintenance (though with a higher loss ratio)
GPS
For high-line vehicles, only automotive protection chemicals, such as paint and fabric treatments, should be included in reinsurance programs, other coverages managed through retro programs where no risk is carried on losses.
What Products Shouldn’t Be Included?
Dealers should be cautious with high-line cars in reinsurance programs. These vehicles often generate claims too large to cover without significant reserves, making them a poor fit for these programs.
Take Control of Your Reinsurance Strategy
Many dealers struggle to stay on top of the intricacies of their reinsurance plans due to the overwhelming demands of running a dealership. However, it’s vital to have a clear understanding of what you’re paying out and the services you’re receiving. Engaging with your brokers, accountants, financial officers, and agents during quarterly reviews can provide the clarity needed to make informed decisions.
By staying proactive and engaged with your reinsurance strategy, you can better protect your dealership’s financial health and build wealth for the long term.
Frank Torchia is a regional vice president with Vanguard Dealer Services.
EDITOR’S NOTE: This article was authored and edited according to F&I and Showroom editorial standards and style. Opinions expressed may not reflect that of the publication.
Originally posted on F&I and Showroom
More Industry
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →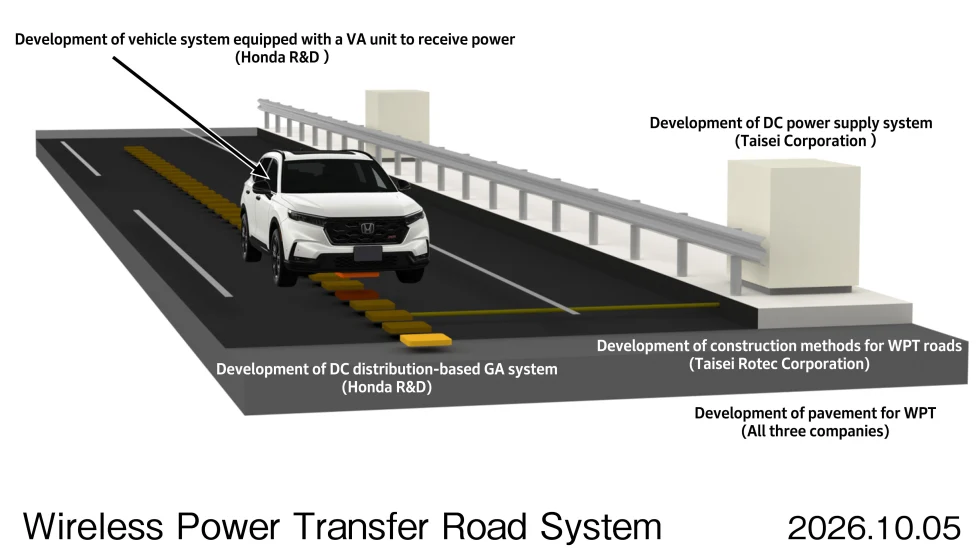
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →