CFPA Bill Added to Larger Financial Reforms Package
A House committee has incorporated the Consumer Financial Protection Agency (CFPA) into a larger financial reforms package, called the Wall Street Reform and Consumer Protection Act. The new bill, HR 4173, was finalized by the House Financial Services Committee on December 2, and will be introduced to the House of Representatives this week.
HR 4173 includes the reforms called for in HR 3126, the Consumer Financial Protection Agency Act of 2009, and eight other pieces of legislation approved by the committee to address the causes of last year’s financial meltdown.
The Wall Street Reform and Consumer Protection Act include the following provisions:
Consumer Protections: Creates the Consumer Financial Protection Agency (CFPA), a new, independent federal agency solely devoted to protecting Americans from unfair and abusive financial products and services.
Financial Stability Council: Creates an inter-agency oversight council that will identify and regulate financial firms that are so large, interconnected, or risky that their collapse would put the entire financial system at risk. These systemically risky firms will be subject to heightened oversight, standards, and regulation.
Dissolution Authority and Ending “Too Big to Fail”: Establishes an orderly process for dismantling large, failing financial institutions like AIG or Lehman Brothers in a way that ends bailouts, protects taxpayers, and prevents contagion to the rest of the financial system.
Executive Compensation: Gives shareholders a “say on pay” – an advisory vote on pay practices including executive compensation and golden parachutes. It also enables regulators to ban inappropriate or imprudently risky compensation practices, and it requires financial firms to disclose any compensation structures that include incentive-based elements.
Investor Protections: Strengthens the SEC’s powers so that it can better protect investors and regulate the nation’s securities markets. It responds to the failures to detect the Madoff and Stanford Financial frauds by ordering a study of the entire securities industry that will identify needed reforms and force the SEC and other entities to further improve investor protection.
Regulation of Derivatives: Regulates, for the first time ever, the over-the-counter (OTC) derivatives marketplace. Under the bill, all standardized swap transactions between dealers and “major swap participants” would have to be cleared and traded on an exchange or electronic platform. The bill defines a major swap participant as anyone that maintains a substantial net position in swaps, exclusive of hedging for commercial risk, or whose positions create such significant exposure to others that it requires monitoring.
Mortgage Reform and Anti-Predatory Lending: Would incorporate the tough mortgage reform and anti-predatory lending bill the House passed earlier this year. The legislation outlaws many of the egregious industry practices that marked the subprime lending boom, and it would ensure that mortgage lenders make loans that benefit the consumer. It would establish a simple standard for all home loans: institutions must ensure that borrowers can repay the loans they are sold.
Reform of Credit Rating Agencies: Addresses the role that credit rating agencies played in the economic crisis, and takes strong steps to reduce conflicts of interest, reduce market reliance on credit rating agencies, and impose a liability standard on the agencies.
Hedge Fund, Private Equity and Private Pools of Capital Registration: Fills a regulatory hole that allows hedge funds and their advisors to escape any and all regulation. This bill requires almost all advisers to private pools of capital to register with the SEC, and they will be subject to systemic risk regulation by the Financial Stability regulator.
Office of Insurance: Creates a Federal Insurance Office that will monitor all aspects of the insurance industry, including identifying issues or gaps in the regulation of insurers that could contribute to a systemic crisis and undermine the entire financial system.
More Industry
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →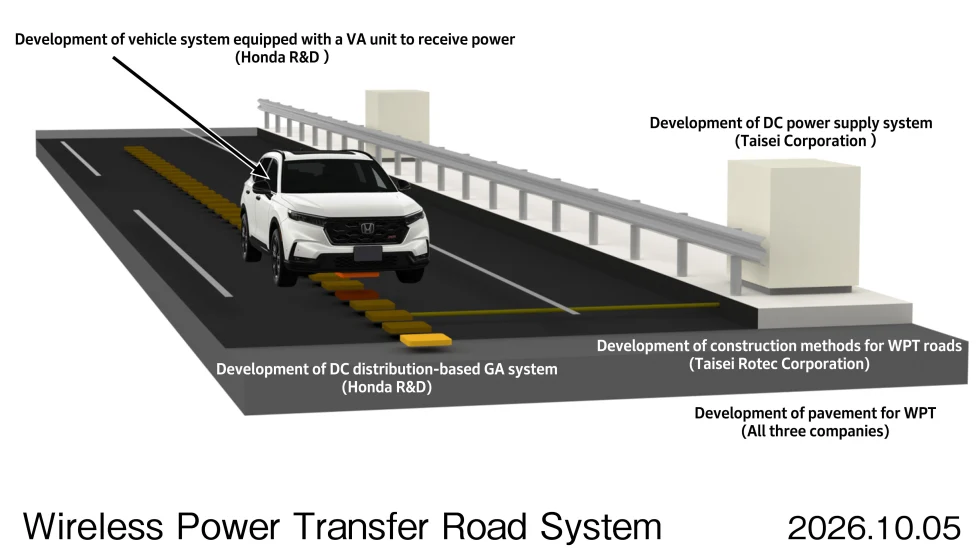
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →