CFPB Responds to House Republicans
Washinton, D.C. — In August, the Consumer Financial Protection Bureau (CFPB) responded to a letter submitted by 35 Republican members of the U.S. House of Representatives. The letter requested information on the CFPB’s use of the disparate impact theory in its review of dealer participation programs auto finance sources offer to dealers.
In March, the bureau issued guidance that said finance sources could be held liable if the CFPB found that dealer participation programs create a bias that causes minority groups to pay higher rates. Members of Congress, however, were concerned that the bureau had not disclosed the methodology it is using to determine if discrimination occurred.
“We are all strongly opposed to any discrimination in lending,” the letter, which was issued by House Republicans on June 20, stated. “However, it is highly concerning that the agency is issuing such significant new directives without affording the public a proper opportunity to comment on its methodology and analysis for determining whether discrimination has occurred and without addressing the effect of its directives on consumer financing and choice in the intensely competitive auto lending market.”
In response to why it did not seek public comment on its indirect auto lending guidance, the CFPB said the Administrative Procedure Act “does not mandate notice and comment for general statements of policy, non-binding informational guidelines and interpretive memoranda,” the CFPB Monitor reported yesterday.
According to the CFPB Monitor, the CFPB did not offer any specifics regarding its methodology. Instead, the bureau reiterated that it uses surname and geographic proxies to conduct its analysis using unspecified, publicly available methods.
In June, the bureau responded to a similar letter sent in May by House Democrats.
“The evaluation of whether an indirect auto lender is in compliance with the “Equal Credit Opportunity Act requires multiple steps,” the CFPB wrote in its June 20 response. “A typical fair lending examination of an indirect auto lender would include a review of credit denials, interested rates quoted by the lender to the dealer (called “buy rates”), and any discretionary mark-up of the buy rate by the dealer (the interest rate quoted by the dealer to the consumer minus the “buy rate”).
“Determining whether discrimination has occurred is a case-specific and fact-intensive inquiry.”
More Industry
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →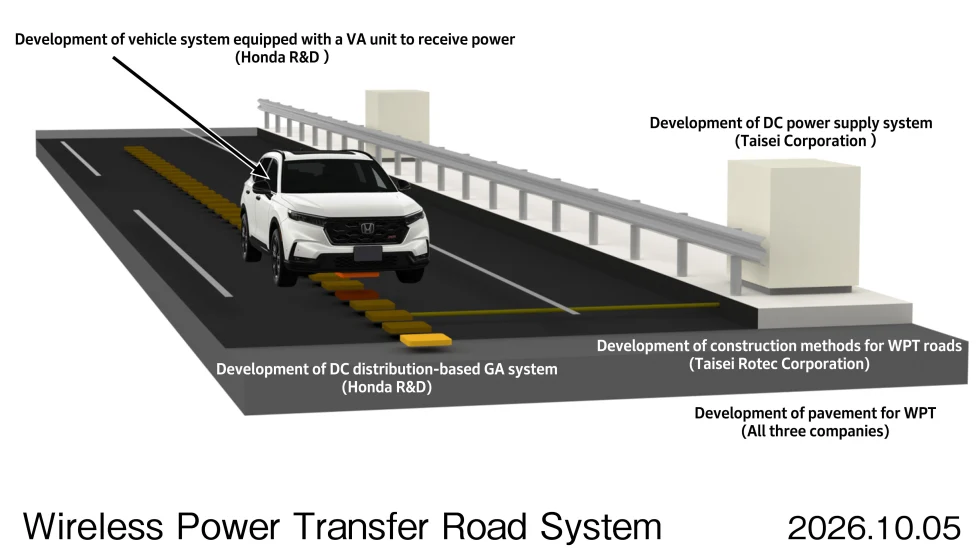
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →