State of the Automotive Finance Market: Q3 2022
New Experian report finds average loan terms extend for new and used vehicle loans as interest rates rise.

New Experian reports finds average loan terms extend for new and used vehicle loans as interest rates rise.
IMAGE: Experian
Schaumburg, Ill. — Against the backdrop of the ongoing inventory shortage, the average used vehicle loan amunt continues to grow, but at a notably slower rate. According to Experian’s State of the Automotive Finance Market Report: Q3 2022, the average used vehicle loan amount increased 8.59% year-over-year, reaching $28,506. This is significantly smaller than the increase seen this time last year, as in Q3 2021 there was a 21.37% year-over-year increase, reflecting how quickly used vehicle values rose as new vehicle inventory declined. The average loan amount for a new vehicle also saw an increase, growing from $37,753 in Q3 2021 to $41,665 in Q3 2022.
“Since the start of the inventory shortage, used vehicle values rose at a staggering rate, and that appears to be slowing, which is a positive sign for consumers looking to purchase a vehicle,” said Melinda Zabritski, Experian’s senior director of automotive financial solutions. “While average loan amounts and monthly payments are continuing to grow, there are many contributing factors, such as the rise in interest rates. Leveraging data to better understand these factors will help lenders and dealers make informed decisions in the days to come.”
In the third quarter of 2022, the average interest rate was 5.16% for new vehicle loans, and 9.34% for used, up from 4.09% and 8.12%, respectively, last year. The growth in average loan amounts and interest rates were also reflected in average monthly payments, which went from $618 in Q3 2021 to $700 in Q3 2022 for new vehicles, and from $472 to $525 for used vehicles, in the same time frame. The average vehicle loan term also increased, from 69.51 months for new vehicles in Q3 2021, to 69.73 months in Q3 2022. The increase was larger for used vehicles, jumping from 66.97 months in Q3 2021 to 68.08 in Q3 2022.
Finance Market Share Sees Shifts
Credit unions held the largest market share of automotive finance in Q3 2022, surpassing banks, which had long been the largest lender in automotive finance. Credit unions held 28.44% of vehicle financing this quarter, a 40% year-over-year increase, as they held 20.21% in Q3 2021. Banks declined in market share, from 32.51% in Q3 2021 to 27.32% in Q3 2022, with similar trends seen for captive lenders, decreasing from 26.64% to 21.89%, year-over-year.
Another shift seen in the finance market is the significant decline in leasing for new vehicles, which dropped from 27.28% in Q3 2021 to 18.01% in Q3 2022. The types of vehicles consumers are looking to lease continues to evolve, with the top 10 models leased comprised of exclusively larger vehicles, such as full-size trucks, and SUVs. Leases often have a lower monthly payment than loans, with the average difference between a loan and lease payment clocking in at $133 in Q3 2022.
“Opting for a lease is one way that consumers look to manage their monthly payments, which is often how they shop for a vehicle,” Zabritski continued. “Affordability will continue to remain top of mind as a decline in leasing, coupled with the lack of new vehicle inventory, will impact availability of used vehicles in a few years.”
Additional Findings for Q3 2022
Outstanding automotive loan balances increase from $1.2 trillion in Q3 2021 to $1.3 trillion in Q3 2022.
While most growth was in prime lending (reaching 46.67%), deep subprime financing did increase slightly, from 1.76% in Q3 2021 to 1.85% in Q3 2022.
Pickup trucks saw an increase in financing, from 15.84% in Q3 2021 to 17.19% in Q3 2022.
The average credit score for vehicle loans continued to increase, from 733 to 738 year-over-year for new vehicle loans, and from 675 to 678 year-over-year for use vehicle loans.
Wyoming leads with the largest percentage of loans for used cars in Q3 2022 at 85.4%, while New York has the lowest at 65.5%.
To learn more click here.
Originally posted on F&I and Showroom
More Industry
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →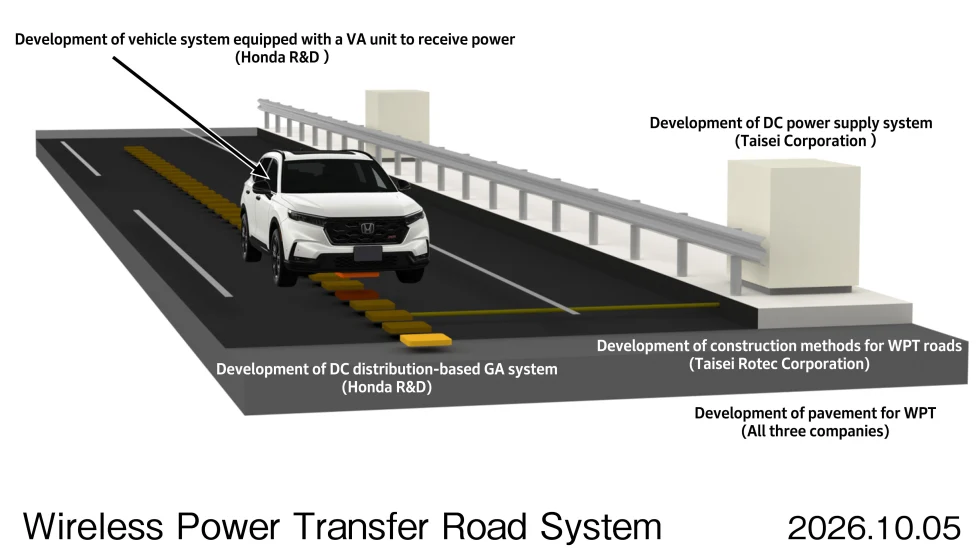
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →