

How to Optimize Liquidity in a Fluid Environment
It's wise to not take your dealership's banking relationships for granted.
Identify areas of potential risk or opportunity by asking yourself a series of questions.
Pexels/Oleksandr P
“Cash is king” has been an historical truism for decades, but we’ve outpaced this iconic catchphrase. Liquidity management is the new axiom today, and for good reason — it’s no longer as simple as managing cash flow and capital funds. Auto dealership operators understand business success in today’s economy requires a multifaceted approach. With challenges ranging from fluctuating interest rates to looming fraud events, it might be time to reassess financial strategies, within and outside the organization. Here’s where to start:
Benchmark Your Banking Relationship
Liquidity management is one of the main pillars of a company’s treasury department because it ensures solvency. But perhaps more important, prudent liquidity management and the right financial resources can help increase efficiencies and even profitability. To help identify areas of potential risk or opportunity, here are some questions to ask yourself:
How can I protect my dealership against fraud? Fraud can pose a significant threat to a dealership’s financial stability. Your bank should have state-of-the-art technologies that provide robust security measures and automation tools to help safeguard your assets and transactions.
Am I getting compensated fairly for my deposits? Banks that offer a wide range of products and services can provide opportunities to reduce costs and earn credits against banking fees.
Is my bank talking about liquidity? Liquidity management is paramount in today’s financial environment. Your bank should actively discuss strategies to help you optimize this critical aspect of your business.
How does my bank handle surcharge laws and merchant processing issues? A seasoned financial consultant will keep you informed about the latest regulations and requirements, plus help develop strategies to minimize associated costs.
What’s the downside of using my personal credit card for business expenses? In addition to tying up a credit line you might need for personal needs or emergencies, business credit card transactions will effectively appear on your personal credit report. It’s best to separate personal and professional liabilities, which is easy to do with an integrated banking strategy.
Is my payroll automated? Managing payroll and writing checks can be a time-consuming task that drains resources and creates a vibrant channel for check fraud. Automating this process not only saves time but ensures your employees are paid accurately, securely and on time.
It’s likely your answers to the questions above have provided a baseline for your liquidity position and at least a skeletal road map for how to improve it. But you may also be asking yourself, “How do I achieve all of these goals without complicating the process with multiple banking relationships?”
Not all Banks Are the Same
It’s important for your business to choose a bank that offers the comprehensive products and services necessary to optimize liquidity. Choosing a financing provider doesn’t need to be intimidating or complicated. Here are questions to consider:
Do they understand my business and how transactions need to be customized to meet my business requirements?
Do they take the time to listen to me and demonstrate an interest in wanting to see my business succeed?
Is this a well-established lender that has survived economic ups and downs and consistently remains committed to the automotive industry?
Keep in mind that a bank doesn’t need a physical location near your business in order to work with you. If you find an ideal financing provider, it can likely work successfully with you anywhere in the United States.
Business owners should be bold in asking their potential financing provider the tough questions so they can truly evaluate and select the ideal team.
Brian Bateman is a national manager for dealer finance at KeyBank, which he joined in 2015. He has more than 30 years of automotive industry experience.
EDITOR'S NOTE: This article was authored and edited according to Auto Dealer Today editorial standards and style. Opinions expressed may not reflect that of the publication.
Originally posted on Auto Dealer Today
More Industry
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →
First-Half Dealership Deals Up
Buy-sell activity shows that acquirers are looking for value and scale as many retailers seek to leave an increasingly competitive and complex market, Kerrigan Advisors reports.
Read More →
Kia Closes Out Summer With a Bang
Its U.S. subsidiary broke multiple records in August, in part due to a surge of demand for hybrids models.
Read More →
Indiana Dealership Changes Hands
A 30-year-old Ford dealership in Indiana has a new owner and will soon be undergoing renovations to meet manufacturer requirements.
Read More →
Texas Dealership No Longer in the Family
The Ford store, a longtime cornerstone of the Houston market, is now part of one of the fastest-growing U.S. auto groups.
Read More →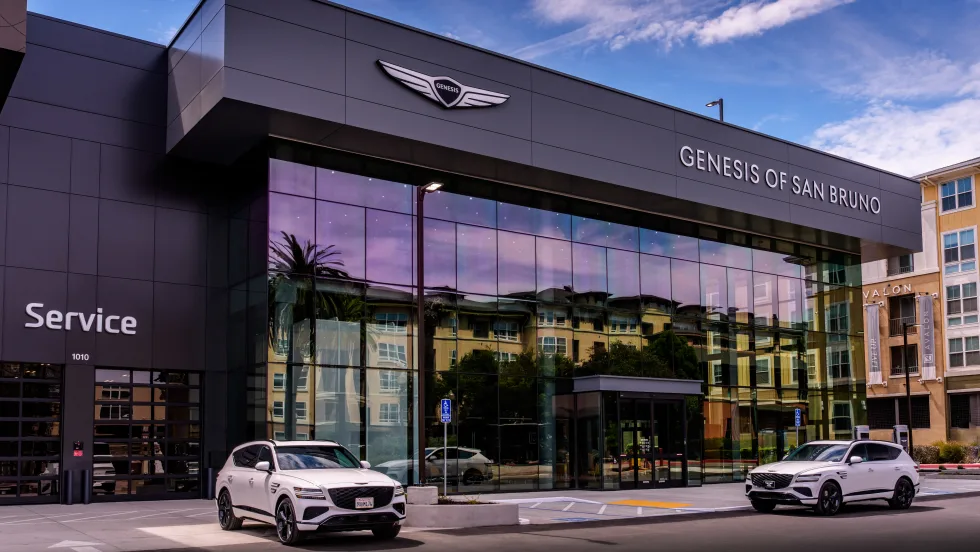
Genesis Grows California Presence
The Cardinale Automotive Group opened its third Genesis rooftop in the Golden State, Genesis of San Bruno, a stand-alone dealership serving the San Francisco Bay Area.
Read More →
August Auto Sales a Mixed Bag
An early forecast shows strong business despite consumer hurdles, and hybrids are a big piece of their affordability coping strategy.
Read More →
EV Market Humming Along
July sales show steady growth as the segment stabilizes from last year’s artificial surge following pullback of federal support.
Read More →
Auto Loan Delinquency Rates Stabilize
Auto loans are a main driver of nonmortgage consumer debt, but delinquency rates stabilized in the second quarter across all credit risk tiers.
Read More →