CFPB Takes Aim at F&I Products
Via F&I Showroom
Less than two months after the Consumer Financial Protection Bureau (CFPB) confirmed it was watching policies related to dealer participation by issuing guidance to indirect auto lenders, the bureau appears to be targeting the sale of extended warranties and other F&I products.
Reports suggest that the CFPB has issued subpoenas to U.S. auto lenders related to the sale of products such as extended-service contracts and other add-ons. Service Contract Industry Council (SCIC) Executive Director and General Counsel Timothy J. Meenan said the move is “possible and probable” based on media reports, but he has yet to receive confirmation.
“It appears that they are looking at lending practices for sales of automobiles, and also looking at issues involving add-on products,” Meenan said.
In March, the CFPB said it would hold lenders that offer auto loans through dealerships responsible for unlawful, discriminatory pricing. It alleged that bank policies which allow auto dealers to mark up the interest rates on retail installment sale transactions in exchange for services rendered have caused a disparate impact, meaning that members of minority groups pay higher rates. Several banking institutions, including Ally Financial, received letters stating that they could face lawsuits under the Equal Credit Opportunity Act (ECOA).
Groups such as the National Automobile Dealers Association (NADA) and the National Association of Minority Automobile Dealers (NAMAD) have denounced the bureau’s actions, as the CFPB has not revealed how it is conducting its analysis. Using the disparate impact theory, the CFPB has taken the position that violations of the ECOA can be pursued based solely on statistics — meaning a lender can potentially be held responsible for unintentional impacts on minorities.
NADA’s Director of Public Relations, Charles Cyrill, said the organization was not aware of any CFPB action related to F&I add-ons. “We have not received any information about CFPB investigations regarding optional products other than dealer reserve,” he explained.
The CFPB has not publicly confirmed the targeting of F&I products, but a spokesman did not deny recent reports.
“When I look at what the CFPB's been doing with mortgages and with, say, credit card companies, they've gone after things that are potentially misleading,” Meenan said. He explained that while credit card companies have been known to sign up customers for add-on products without their knowledge or understanding, car buyers must sign a contract for F&I add-ons that says, “Yes, I want this.”
Last year, the CFPB reached settlements with credit card issuers such as Capital One Bank, which agreed to refund approximately $140 million to 2 million customers, as well as pay a $25 million penalty for the way it marketed add-on products like payment protection.
“I think those kinds of misleading practices don't really apply to automobile service contracts,” Meenan said. “You can, in the first 45 days, cancel a service contract and get all your money back. And thereafter, you can get the pro rata share back… There are lots of good consumer protections in these products that I think the CFPB will find attractive.”
The CFPB is not the only agency looking at the auto industry. At a panel discussion at George Mason University on May 2, Jon M. Seward, deputy at the U.S. Department of Justice’s Housing and Civil Enforcement Section, said that the DOJ has experienced a shift in referrals of violations from federal bank regulators including the CFPB.
“We’re seeing a lot more referrals involving pricing discrimination allegations in the unsecured consumer lending space; a number of auto-related referrals either involving indirect auto lending or some involving buy-here, pay-here car dealerships,” Seward said in a video.
In December 2012, the department signed a memorandum of understanding with the CFPB aimed at strengthening their coordination in connection with fair lending investigations. That’s why, Meenan says, “We’re not taking anything lightly… We are in a fact-finding mode using local council and others to find out what it is the CFPB is after.”
More Industry
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →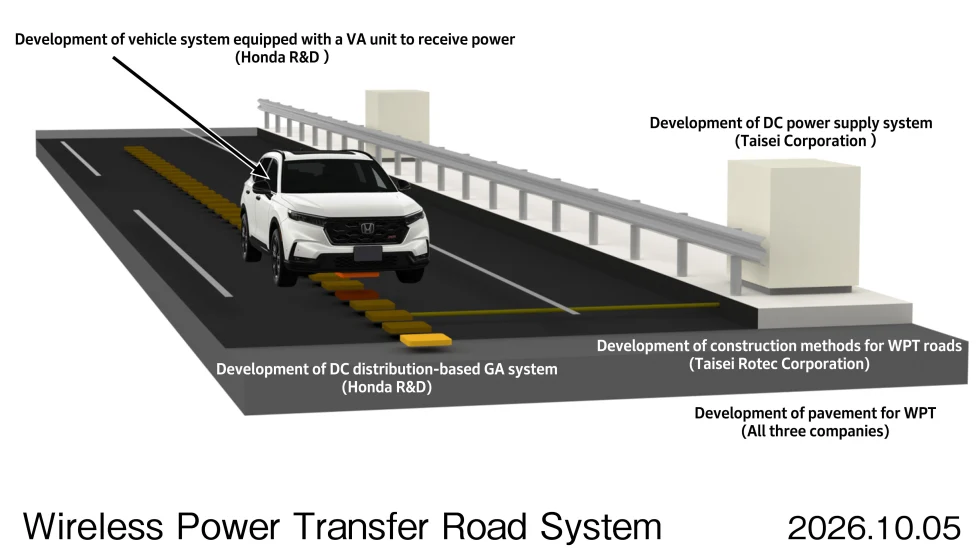
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →