Lenders Making The Road To Auto Financing Easier to Travel
As car buyers head back into dealerships after a two-year drought, they're being greeted by rock-bottom interest rates on auto loans, eye-popping lease deals and a renewed willingness to lend to people with spotty credit.
Banks are on firmer financial footing, helped by government aid and renewed demand for auto loans that are packaged and sold as securities, a market that raises money and allows banks to write more loans. Buyers, too, are gaining confidence. U.S. auto sales rose 20 percent in February to the highest monthly pace since "cash for clunkers" in August 2009, reported The Detroit News.
This month, General Motors, Chrysler, Ford, Nissan and others have been offering zero percent interest rates on auto loans. Luxury makers such as Acura and Cadillac have lease deals with zero percent down. Banks have cut their interest rates on auto loans in half.
"If you feel comfortable purchasing today, the deals are out there to be had," said Mark Hawks, 40, an information technology specialist from suburban Washington, D.C., who shaved thousands of dollars off the sticker price of the Ford Taurus SHO sport sedan he bought in December.
Hawks has a credit score of 780, which puts him in the highest tier of borrowers. He was pre-approved through his credit union for a five-year loan with a 3.99 percent annual interest rate. But his dealer beat that, offering a 3.79 percent rate with no payment for 90 days through Fifth Third Bank. The dealer also kicked in a $2,000 rebate and the trade-in value of Hawks' eight-year-old Subaru. Final price of the new car: $33,000, compared with a sticker price of $46,000.
Here are some reasons for the great deals:
Lower rates. Buyers are paying an average annual percentage rate of 3 percent for new cars financed in February, down from nearly 4 percent in the same month a year ago, says auto research site Edmunds.com. That's one of the lowest rates since before the economic downturn.
Banks, credit unions and automotive financing companies are in fierce competition to loan you money. While credit unions and finance companies once offered the lowest rates, banks now have more competitive financing.
With short-term rates near zero percent, banks that offered loans at 7 percent or 8 percent can now profit off 3 percent or 4 percent, says Greg McBride, a financial analyst with the personal finance website Bankrate.com.
More loans for subprime borrowers. Unlike much of 2010, when the auto loan market was open mainly to buyers with the best credit, people with weak credit histories now are having an easier time finding loans because of the competitive market. The percentage of new-car auto loans going to subprime buyers — generally those with credit scores below 680 — rose 18 percent in the last three months of 2010 over the same period the year before, according to Experian Automotive.
Better leasing deals. Leasing is making a comeback. That's a boon for people seeking lower monthly payments on a car or truck. Leases made up a quarter of new-car transactions in February, Edmunds says. That was the highest single month for leasing since November 2005.
Generally, leasing means you pay less per month than you would on a car loan. The reason: You're only paying off the amount the car will depreciate before you turn it in. When you buy, you're paying for the whole car, plus finance charges.
Typically, about 20 percent of new cars are leased. But the bottom fell out of that market at the beginning of the downturn because there were too many used cars and not enough demand for cars coming off lease. Leasing fell to 16 percent of the market in 2009.
But as the recession progressed, used cars became scarce as people looked for cheaper wheels. That caused used car prices to rise. Now, lenders are more willing to take on a lease, knowing the car will be worth something when the lease is up.
Interest rates are likely to stay low this year, as the economy continues to recover. That will help keep loan terms attractive. Competition also remains fierce among car companies. GM said this month that it expects to dial back on lease deals and other incentives as the year goes on.
But even though deals are good, lenders have learned their lessons from the bust. Hawks, with his stellar credit, couldn't match the deal he got on his Subaru in 2002. Back then, he paid 2.9 percent annual interest rate on a five-year loan.
More Industry
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →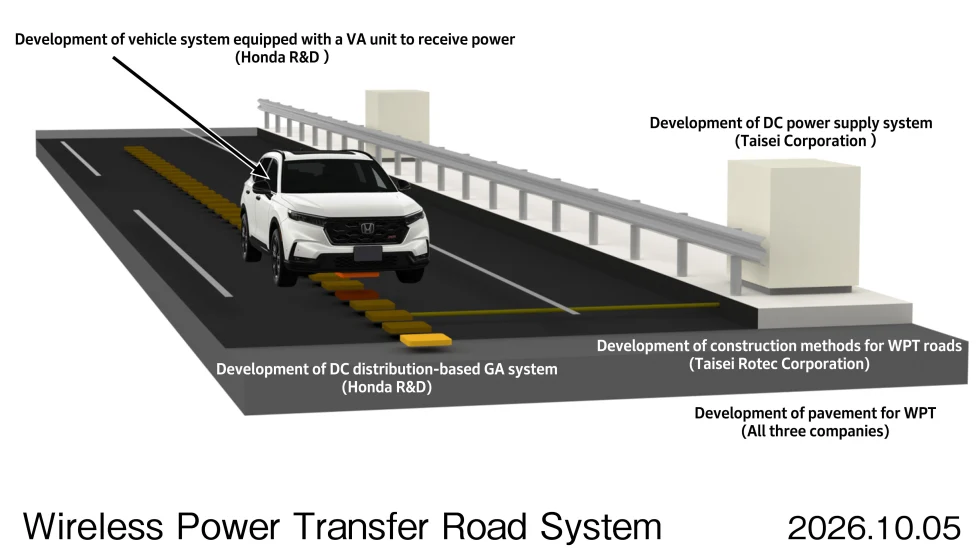
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →