NADA Issues Second Quarter 2020 Auto Sales Analysis
During this quarter, retail sales recovered much more quickly than fleet sales from the effects of the COVID-19 pandemic.

During this quarter, retail sales recovered much more quickly than fleet sales from the effects of the COVID-19 pandemic.
Image by Jay George from Pixabay
The National Automobile Dealers Association (NADA) issued an analysis of U.S. auto sales and the economy following the second quarter of the year, a period when dealers and the U.S. economy continued experiencing the impact the coronavirus pandemic, but also began seeing an upturn.
It is unlikely that we will make up all of the production lost during the shutdowns, but vehicle manufacturers are working through previously schedule summer vacation shutdowns to try and catch up.
“Vehicle sales have continued to show signs of recovery after bottoming out in April at a SAAR of 8.6 million units, the lowest on record since the federal government began tracking auto sales,” said NADA chief economist Patrick Manzi. “June’s SAAR of 13.05 million units was a significant improvement over April.”
During this quarter, retail sales recovered much more quickly than fleet sales from the effects of the COVID-19 pandemic. Fleet sales were down year-over-year by a 72% in May while retail sales only fell by 17%. And in June fleet sales were down year-over-year by 73% while retail sales were off by only 6%. Several major rental car companies have cancelled or significantly reduced their fleet orders this year causing fleet sales to fall dramatically.
The retail sales recovery has been driven by generous manufacturer incentives. According to J.D. Power, incentive spending is expected to average $4,349 per unit, an increase of $383 from June 2019 and a record level for the month of June. After reaching an all-time record of $4,981 per unit in April 2020, incentive spending decreased in May and June. For the rest of the year, incentive levels are expected to be elevated compared to last year but likely won’t be as high as in April 2020.
From an inventory perspective, dealers have seen significant reductions compared to the same time last year given plant shutdowns and robust recovery in retail demand. At the end of June, inventory was 2.6 million units, down from 3.9 million units this time last year, with a shortage of inventory in popular segments. Pickup truck inventory was particularly low due to strong sales resulting from record incentives offered by manufacturers in April and May.
According to Wards Intelligence, the forecast for Q3 2020 North American vehicle production is 3.81 million units – down 7.5% compared to Q3 2019. Through the first nine months of 2020, North American vehicle production is expected to total 9.13 million units – down 29.2% compared to the first 9 months of 2019.
“It is unlikely that we will make up all of the production lost during the shutdowns, but vehicle manufacturers are working through previously schedule summer vacation shutdowns to try and catch up,” added Manzi. “However, the decline in fleet sales frees up capacity for the production of additional vehicles for retail sales.”
NADA’s new light-vehicle sales estimate remains between 13 million and 13.5 million units for the year.
At the macrolevel, virus-related economic recovery legislation provided the U.S. economy a much-needed boost. The $2.2 trillion dollar stimulus, the largest stimulus package in modern history, provided vital Paycheck Protection Program (PPP) loans to small businesses, including truck and car dealers, allowing dealers to retain employees even in spite of forced closures from the pandemic.
June’s jobs report showed that the U.S. economy added a record 4.8 million jobs. However, despite a large number of American’s returning to work, there are still 15 million Americans unemployed. This data was captured in early June before recent spikes in COVID infections in certain geographic parts of the country. These spikes could cause volatility in the jobs numbers in the coming months.
Originally posted on Auto Dealer Today
More Industry
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →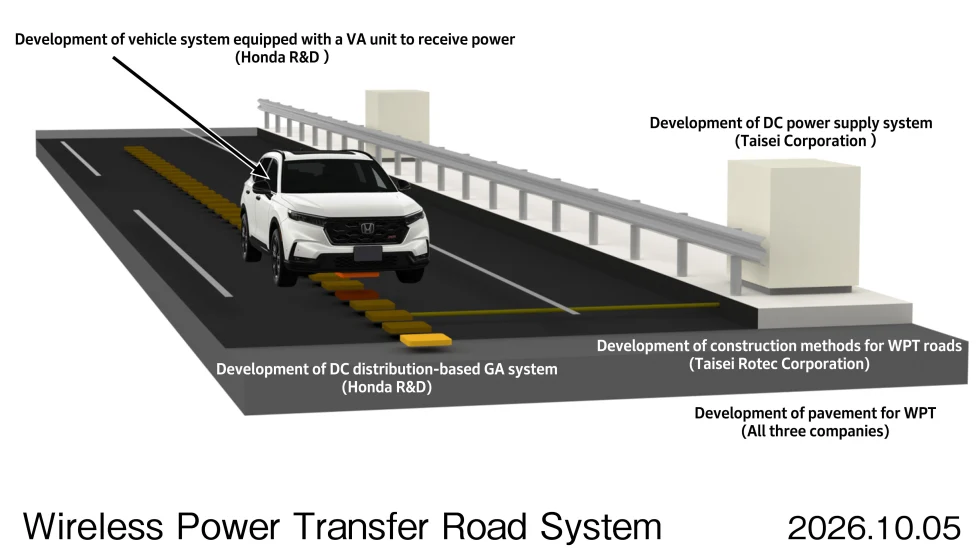
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →