New Experian Report Shows Auto Industry Continued to Rebound in Q3
Despite smaller percentage of financed vehicles, outstanding loan balances grew 2.8% year-over-year to more than $1.2 trillion.

Despite smaller percentage of financed vehicles, outstanding loan balances grew 2.8% year-over-year to more than $1.2 trillion.
SCHAUMBURG, Ill.— Throughout the pandemic, the automotive industry has been one of the reference points in assessing the recovery, and according to findings from Experian’s Q3 2020 State of the Automotive Finance Market report, the automotive sector continues to show positive trends.
The improvement is a positive sign for the country’s economic recovery.
Prior to the pandemic, delinquency rates were considered a barometer of health for the automotive finance market, and this continues to be true today. According to the report, 30- and 60-day delinquency rates improved in Q3 2020, reaching 1.56% and 0.51%, respectively. Comparatively, a year ago, the 30-day delinquency rate was 2.25% and the 60-day delinquency rate was 0.75%.
“While the decline in 30- and 60-day delinquency rates is a positive trend for the industry, particularly with some of the accommodation programs coming to an end, we do need to consider the impact these programs have had on consumers,” said Melinda Zabritski, Experian’s senior director of automotive financial solution. “Some consumers likely leveraged financial assistance programs to manage through hardship, so it’s important for lenders to keep a close eye on how delinquency rates evolve over the coming quarters. Nonetheless, the improvement is a positive sign for the country’s economic recovery.”
Beyond influencing consumers’ ability to manage monthly payments, the pandemic also impacted sales volume. However, despite fewer vehicle sales, outstanding loan balances still grew 2.8% from a year ago, reaching $1.2 trillion. This also comes at a time where a smaller percentage of vehicles are being financed. The percentage of new vehicles with financing was 82.43% in Q3 2020 compared to 86.99% the previous year. Similarly, the percentage of used vehicles with financing was 33.71% in Q3 2020 compared with 39.79% over the same period. It is important to note, the drop in the percentage of vehicles with financing can also be attributed to an increase in cash transactions.
Prime Consumers Shift Back to Used Vehicles
During the first few months of the pandemic, automakers offered new vehicle incentives to improve sales. As a result, we saw prime borrowers opt for new vehicles, reversing a trend we observed in previous quarters. With fewer incentives offered in Q3 2020, a higher percentage of prime borrowers shifted back to used. Prime and super prime borrowers made up 55.3% of used vehicles financed during the quarter, a new high for used vehicle lending. 30- and 60-day delinquency rates improve in Q3 2020, as the automotive industry continues to rebound Page 2 of 3
The shift back to the used vehicle market is likely driven by continued affordability conversations. Both the average new and used vehicle loan amounts saw increases in Q3 2020. The average loan amount for a new vehicle increased more than $2,000 over the previous year, reaching $34,635, while the average loan amount for a used vehicle saw a $945 increase to $21,438 over the same period. The increases in new and used loan amounts could also be attributed to consumer preference, with consumers leaning toward larger, more expensive vehicles. Small SUVs were the most purchased vehicles, making up 26.01% of loans in Q3 2020, followed by mid-sized SUVs at 24.15%.
Despite the increases in average loan amounts, the increases in average monthly payment weren’t as sharp. In fact, the average new vehicle payment increased $11 year-over-year, reaching $563 in Q3 2020, and the average used vehicle payment increased $6 to $397, over the same period. While the average loan amount for new and used vehicles saw significant increases, the smaller uptick in average monthly payment is due to an increase in loan terms and lower interest rates. The average loan term for a new vehicle increased slightly to 69.68 months in Q3 2020, up from 68.98 months, while the average loan term for used vehicles increased from 64.49 months to 65.15 months. The average interest rate for a new vehicle loan saw sharp decrease from 5.38% in Q3 2019 to 4.22% in Q3 2020, while the average interest rate for a used vehicle dropped from 9.09% to 8.43% over the same period.
“With affordability still top of mind, particularly during the pandemic, lower interest rates have certainly helped consumers keep monthly payments at a manageable level,” Zabritski continued. “As the market evolves and financial situations shift, it’s important for lenders and dealers to stay close to the trends and make strategic decisions that help keep the industry moving forward and consumers in their vehicles.”
Additional findings for Q3 2020:
Deep subprime loans remained under 3% in Q3 2020, with overall subprime lending at a record low of 19.23%.
Average credit scores saw a sharp increase for new vehicles, jumping from 728 in Q3 2019 to 732 in Q3 2020. The average credit score for used vehicles also saw a one-point increase from 664 to 665 year-over-year.
New vehicle leasing continued decrease in Q3 2020, comprising 26.2% of new vehicle financing, compared to 30.27% in Q3 2019.
Captive lenders continued to increase market share, from 30.85% in Q3 2019 to 34.49% in Q3 2020. Buy-here-pay-here lenders saw a slight increase, from 4.32% to 4.69%, while all other lenders saw year-over-year decreases.
To view the entire Q3 2020 State of the Automotive Finance Market report webinar, click here.
Originally posted on F&I and Showroom
More Industry
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →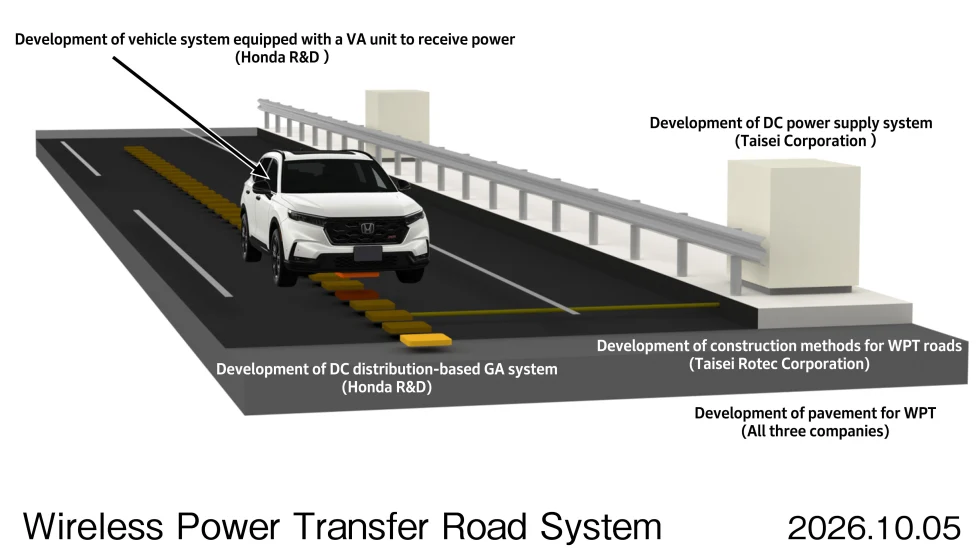
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →