New York Financial Regulator Uses Dodd-Frank to Sue Auto Lender
Via NYTimes
By his own admission, even New York’s top financial regulator did not know he could use the Dodd-Frank law to enforce consumer protections until very recently.
Once he did, however, Benjamin M. Lawsky, the state’s superintendent of financial services, put the power to use.
On Wednesday, Mr. Lawsky’s office filed a lawsuit against a subprime auto lender in New York, accusing it of violating certain provisions of the Dodd-Frank financial overhaul act.
The move appears to make Mr. Lawsky the first state financial regulator and the second state regulator to take advantage of a weapon many of his peers may not have even known was in their arsenal. And as officials across the country seek to appear tough on wrongdoers after the financial crisis, the action could encourage other state regulators to follow suit.
“The authority is clearly there, but it’s never been used by a state regulator before,” said Alan S. Kaplinsky, a lawyer who leads the consumer financial services group at Ballard Spahr. “Once Lawsky does it, other state regulators are going to look at it.”
Dodd-Frank, which was put into place after the financial crisis, contains provisions that prohibit deceptive, abusive or unfair practices by financial companies. It also allows state regulators to enforce those provisions and grants them broader authority than they would have under state law.
Mr. Lawsky’s complaint, filed in Federal District Court in Manhattan, contends that the Condor Capital Corporation, a subprime auto lender based on Long Island, siphoned millions of dollars away from the accounts of unwitting borrowers. To do this, the company would shut down borrowers’ access to online accounts after a loan had been repaid, leaving them unable to see whether an insurance payoff, overpayment or other transaction had left excess money behind, according to the suit.
Condor is also accused of having little or no standards for safeguarding its customers’ personal information. In one instance, examiners found “stacks of hundreds of hard-copy customer loan files lying around the common areas of Condor’s offices.”
The company’s executive vice president, Todd Baron, also stored “backup” tapes that contained confidential customer information without encryption at his home, according to the suit, which also names Condor’s owner, Stephen Baron, as a defendant.
“Simply put, Condor cannot be trusted to service its customers’ loans or handle their funds and data in a safe and lawful manner,” the suit says.
Soon after the suit was filed, a judge granted Mr. Lawsky’s office a temporary restraining order to freeze Condor’s accounts and operations, a spokesman at the department said. The company held more than 7,000 loans to New York State residents with outstanding balances of more than $97 million at the end of 2013, according to the complaint. Across the country, the company’s loan portfolio contained outstanding loans of more than $300 million.
A receptionist at Condor, who declined to give her name, said the company had no comment on the suit.
In his pursuit of Condor, Mr. Lawsky can seek restitution and the ability to install a receiver to run the company. He can also try to move the case into federal court, which would give his office the ability to seek relief for all of Condor’s customers, not just those based in New York. Condor operates in 30 states, according to its website.
But few state regulators have taken advantage of this ability to cast a wider net.
In March, Lisa Madigan, the Illinois attorney general, used the authority granted under the Dodd-Frank Act to sue a payday lender she accused of intentionally deceiving borrowers.
“Once Lawsky does it, other state regulators are going to look at it, and look at what Madigan did and I think it will be the beginning of a lot of additional lawsuits being brought by state A.G.s and state regulators predicated on federal law,” Mr. Kaplinsky said. “I think it will mark the beginning of a trend.”
State regulators had fewer options to pursue banks and other financial companies before the financial crisis, when enforcement was largely left to federal agencies. After the crisis, however, the government had an interest in expanding the states’ power.
“It was a reaction to the feeling at the time that the federal government had largely run roughshod over the rights of states when it came to dealing with the mortgage crisis,” Mr. Kaplinsky said. “This was a way of leveling the playing field and for getting support from the various states for the enactment of Dodd-Frank.”
More Industry
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →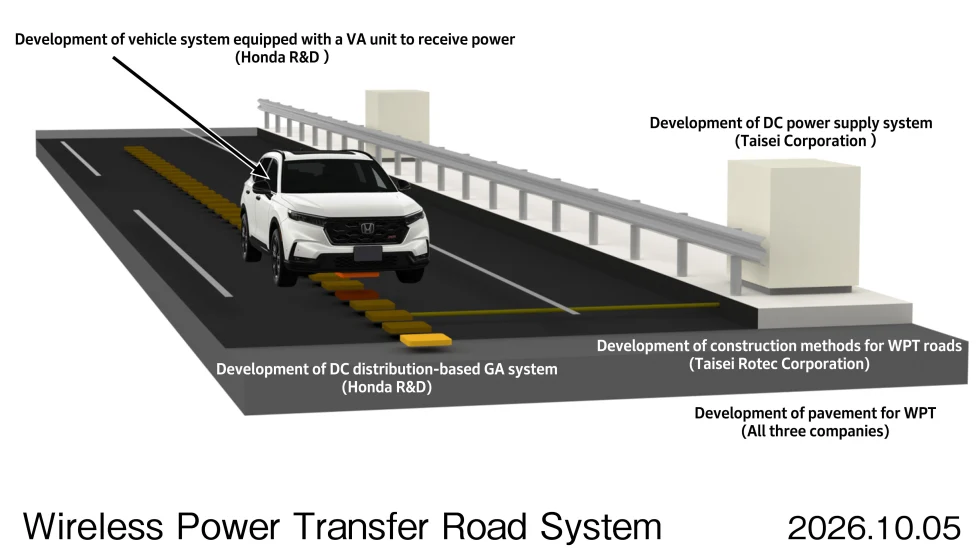
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →