Pew: CFPB Small-Dollar Rule ‘Would Not Adequately Protect Borrowers’

WASHINGTON, D.C. — The Consumer Financial Protection Bureau’s proposed small-dollar lending rule would neither not adequately protect borrowers, nor address the risks created by the shift toward installment credit in the payday and auto title lending market, a new analysis concludes.
Conducted by Pew Charitable Trusts, the analysis outlines the reasons for the shift to installment lending, highlights the riskiest practices, and identifies actions the bureau can other policymakers can take to counter these harms. It also identifies four primary loan characteristics that harm consumers, including unaffordable payments, front-loaded fees, excessive durations, and unnecessary high prices.
“The CFPB proposed rule would require most small loans to be repayable in installments, which would represent a significant improvement, but that change alone is not enough to make these loans safe,” the nonprofit organization stated. “In 13 of the 39 states where they operate, payday and auto title lenders issue only high-cost, single-payment loans, but in the other 26, they are already making installment loans with annual percentage rates of 200% to 600%.
“These high-cost installment loans would still be permitted under the CFPB standards.”
The analysis identified four primary loan characteristics that harm consumers. They include unaffordable payments, front-loaded fees, excessive durations, and unnecessary high prices.
Pew’s brief, “From Payday to Small Installment Loans: Risks, Opportunities, and Policy Proposals for Successful Markets,” shows that unaffordable payments can lead to the same types of problems as convention payday loans, including frequent re-borrowing, heave use of overdrafts, and the need for a cash infusion to retire debt — issues the CFPB hoped to address when it proposed its rule this past June.
The brief also shows that large upfront origination fees “effectively penalize borrowers who repay early or refinance, while unreasonably long durations can double or triple borrowers’ costs.”
“Because payday and auto title lenders typically compete on location, customer service, and speed rather than on price, costs for these products, like conventional payday and auto title loans, are unnecessarily high, such as more than $1,000 in fees for a $500 loan,” the brief states, in part.
The brief also lists the following policy recommendations it says will address the four main challenges posed by installment loans:
Establish clear ability-to-repay standards, limiting loan payment to an affordable percentage of a borrower’s periodic income.
Allow only interest charges or monthly fees on the loan, and no other fees.
Require loan to have reasonable repayment durations.
Enact price limit and enable lower-cost providers, including banks and credit unions, to enter the small-dollar loan market.
“The payday loan market is rapidly shifting away from lump-sum lending toward installments, but 400% APR payday installment loans can be harmful, too,” said Nick Bourke, who directs Pew’s small-dollar loans project. “To protect consumers, the CFPB should add to clear product safety standards to its rule, such as limiting installment payments to 5% of a borrower’s paycheck. This safeguard would make exiting loans more affordable and enable banks to offer comparable small credit at prices six times lower than payday lenders, saving millions of borrowers billions of dollars annually.”
The CFPB’s notice of proposed rulemaking for small-dollar loans is open for public comment until Oct. 7. For more on the bureau’s proposal, click here.
More Industry
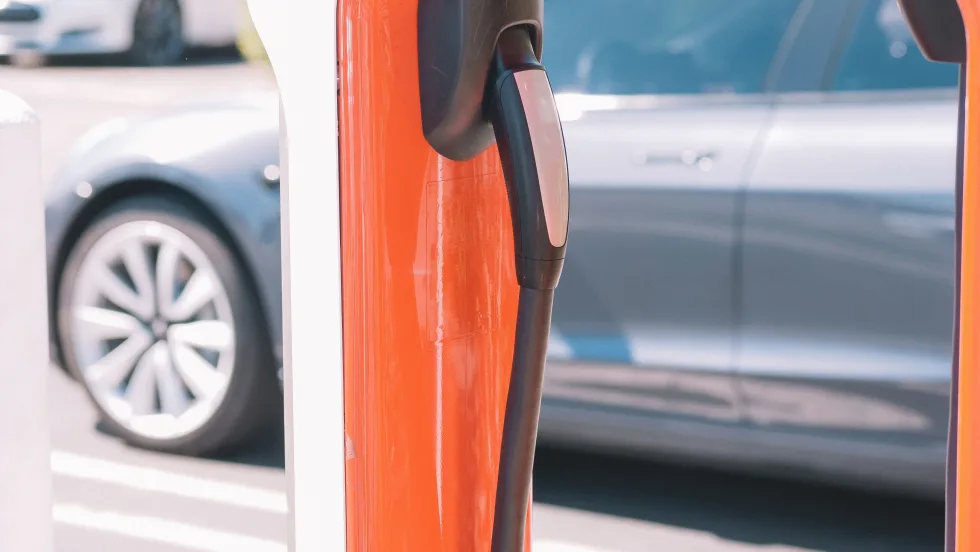
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →