

Subprime Fell to Lowest Share Since 2011 in April
An Equifax review of auto finance data from the first four months of 2019 found subprime’s percentage of total originations fell to 22.7% for all purchases and 9.2% of new-vehicle leases.

Auto finance sources appear to be tightening their lending standards for sub-620 car buyers and lessees.
Photo by Albuquerque Film Office via Flickr
ATLANTA — Equifax analysts say fewer subprime loans for greater amounts drove the category’s share of the U.S. auto finance market down to 22.7%, a 1.7% year-over-year decrease, while that category’s share of all outstanding balances held steady at 18.3%.
In a release, the bureau reported 7.96 million auto loans totaling $183.9 billion originated from January to April. This is a 0.3% decrease in accounts and a 2.3% increase in balances over the first four months of 2018.
Read: Rising Loan Amounts Drive Consumers to the Used-Vehicle Market
Of those, 1.81 million originations went to consumers with a VantageScore 3.0 credit score below 620, a 1.8% decrease from April 2018. These newly issued loans have a corresponding total balance of $33.6 billion, a 1.8% increase.
“It appears lenders are tightening up in the under-620 credit score bucket for both lease and retail contracts.”
The average origination loan amount for all auto loans issued in April was $23,659. This is a 4.5% increase over April 2018. The average subprime loan amount was $19,304, which is a 6.1% increase compared to April 2018.
Total lease originations fell by 3.4% compared with the first four months of 2018. Only 9.2% of leases were written for sub-620 borrowers.
“While overall auto sales have fallen slightly compared to the previous year, we’re seeing active and interesting trends in auto loan originations through April,” said Jennifer Reid, Equifax’s vice president of Automotive Marketing and Strategy. “In particular, while subprime activity continues to grab headlines, it is interesting that the percent of subprime to the total originations are at the lowest level dating back to the end of the recession. Furthermore, we will keep a watchful eye on lender activity, as it appears lenders are tightening up in the under-620 credit score bucket for both lease and retail contracts.”
Originally posted on F&I and Showroom
More Industry
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →
First-Half Dealership Deals Up
Buy-sell activity shows that acquirers are looking for value and scale as many retailers seek to leave an increasingly competitive and complex market, Kerrigan Advisors reports.
Read More →
Kia Closes Out Summer With a Bang
Its U.S. subsidiary broke multiple records in August, in part due to a surge of demand for hybrids models.
Read More →
Indiana Dealership Changes Hands
A 30-year-old Ford dealership in Indiana has a new owner and will soon be undergoing renovations to meet manufacturer requirements.
Read More →
Texas Dealership No Longer in the Family
The Ford store, a longtime cornerstone of the Houston market, is now part of one of the fastest-growing U.S. auto groups.
Read More →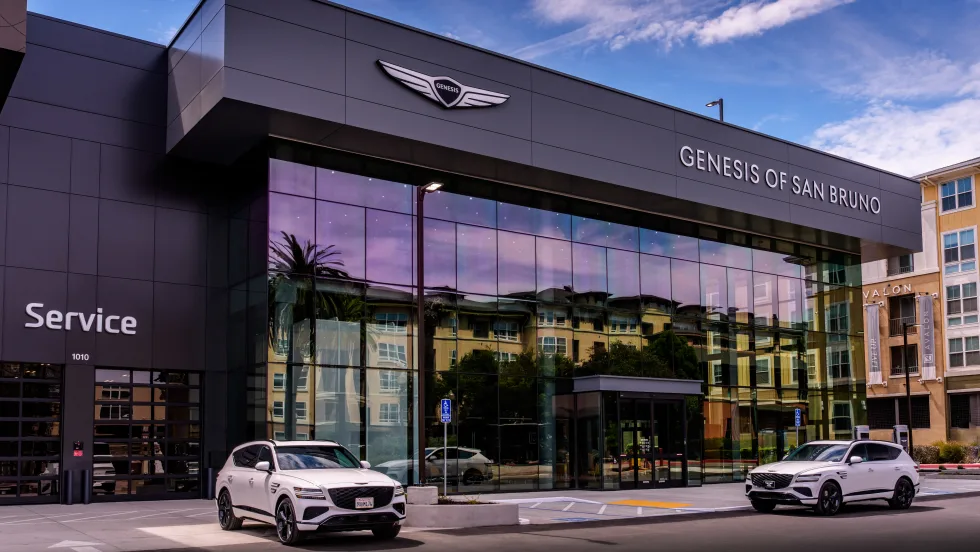
Genesis Grows California Presence
The Cardinale Automotive Group opened its third Genesis rooftop in the Golden State, Genesis of San Bruno, a stand-alone dealership serving the San Francisco Bay Area.
Read More →
August Auto Sales a Mixed Bag
An early forecast shows strong business despite consumer hurdles, and hybrids are a big piece of their affordability coping strategy.
Read More →
EV Market Humming Along
July sales show steady growth as the segment stabilizes from last year’s artificial surge following pullback of federal support.
Read More →
Auto Loan Delinquency Rates Stabilize
Auto loans are a main driver of nonmortgage consumer debt, but delinquency rates stabilized in the second quarter across all credit risk tiers.
Read More →