Dealer Owned Reinsurance Companies– the Offshore Myth
Dealer Owned Reinsurance Companies– the Offshore Myth
Most product administrators and agents know nearly all dealer owned reinsurance programs use an offshore domicile to form and operate their reinsurance programs. Those not directly involved in these programs assume that the location of the reinsurance company must be due to some inherent tax benefits of domiciling the reinsurance company outside the United States. In reality, substantially all of these reinsurance companies make the election under Section 953(d) of the Internal Revenue Code (IRC) to be taxed as U.S. domestic insurance companies for Federal income tax purposes. The alternative would be to have the shareholders report the income on their personal tax returns each year as Subpart F income.
The history of dealer owned reinsurance companies began in the 1950s with the formation of Texas domiciled insurance companies to reinsure credit life and disability insurance. These companies could be formed with as little as $37,500 of initial capital and surplus. When Texas insurance regulations changed in the 1960s, these companies migrated to Arizona.
Arizona initially adopted the original Texas regulations, but gradually increased capital and surplus requirements to $150,000 in the 1980s and increased annual Certificate of Authority renewal and annual filing fees to $4,800. Arizona companies were required to file the NAIC statutory annual statement blanks or “Blue Books,” and were subject to examination by the state insurance department every three years. In its heyday, Arizona had over 1,000 credit life and disability reinsurance companies under its jurisdiction. While many of these companies were owned by banks and finance companies, there were a substantial number of dealer owned reinsurance companies reinsuring the credit insurance products sold through their F&I departments.
From a tax standpoint, these reinsurance companies were subject to corporate income tax as domestic insurance companies, filing Forms 1120-L, 1120-PC and 990, depending upon their mix of business (life and non-life) and annual premium volume. These reinsurance companies were exempt from state income tax in Arizona. Instead, a premium tax was paid by the primary insurer in the state the underlying credit insurance was produced. This premium tax was reimbursed by the dealer owned reinsurance company under the terms of the reinsurance agreement between the two parties.
With the enactment of IRC Section 953(d), dealers became more comfortable with a domicile outside the U.S. and began to look at alternative domiciles outside the U.S. that required less initial and ongoing capital, were significantly less expensive to operate, and were not as heavily regulated. The initial move to an offshore domicile was the British Virgin Islands (BVI). Initial capital for these first offshore programs ranged from $3,000 to $25,000. Annual filing fees were less than $1,000 and, since the direct writer controlled the amount of assets that were in the captive to cover payment of future liabilities, there were no requirements for annual audits or examinations by the regulatory authorities. Since the reinsurance companies had made an election under 953(d) they filed annual Federal income tax returns (Forms 1120-L, 1120-PC or 990), just as they would if they were domiciled in Arizona. The reinsurance companies were not subject to income tax in the BVI.
With the emergence of extended service contracts within the F&I marketplace, offshore domiciles also offered the dealer owned reinsurance company the ability to reinsure both credit insurance and property and casualty insurance products within the same reinsurance company. These two products could not have been commingled in the same reinsurance company within any domicile of the United States.
In general, to reinsure extended service contracts in domestic domiciles, the reinsurance companies would have had to have substantially more capital and surplus than the BVI was requiring. Arizona did enact a statute which would have permitted the reinsurance of extended service contracts which required the same capital and surplus as the credit reinsurer, namely $150,000. The $150,000 was still significantly more than the requirement in the BVI.
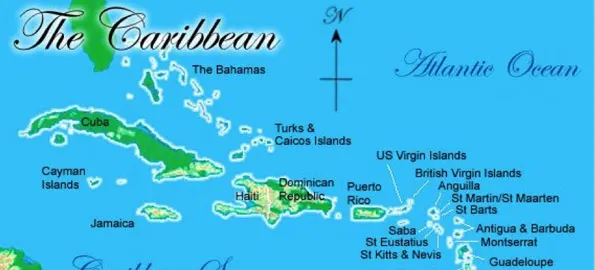
With the passage of more stringent insurance regulations in the BVI in the early 1990s, the dealer owned reinsurance world shifted to the Turks and Caicos Islands (TCI), where a majority of dealer owned reinsurance companies are domiciled today.
Other domiciles currently utilized for dealer owned reinsurance companies include Nevis, Seychelles (where the entities are licensed as International Business Corporations as opposed to reinsurance companies), and the tribal domicile of the Delaware Tribe of Indians in Kansas.
Initial capitalization for these programs has remained relatively stable ($2,500 to $25,000 level), as have annual renewal fees and most regulations. None of these domiciles impose a domestic income tax. They also provide a reduced level of regulation for dealer owned reinsurance programs with highly rated and/or approved primary insurers or administrators. As stated above, the reinsurance companies that make the election under IRC Section 953(d) file annual Federal income tax returns as if they were domiciled within the U.S.
In summary, dealer owned reinsurance companies are not formed offshore for any tax reason. The primary reasons these entities are formed outside the U.S. are lesser initial and ongoing capital requirements, lower regulatory fees and operating costs, and lesser regulation reflecting both the primary insurer’s degree of regulatory scrutiny and its control over the program reserve funds to insure payment of future obligations.
More Industry
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →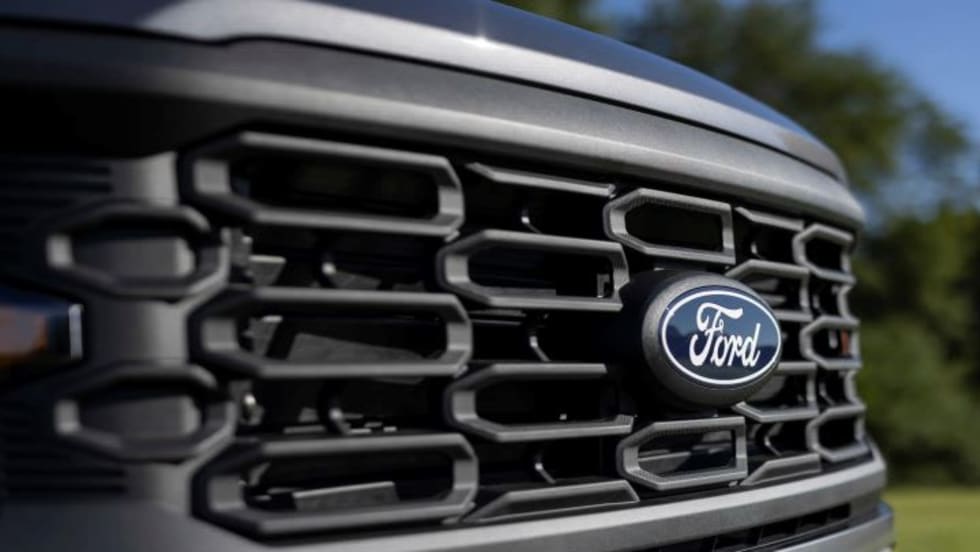
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →