How to Adjudicate Claims for High-Risk Clients

How to Adjudicate Claims for High-Risk Clients
In the P&A segment, working with high-risk clients can lead to financial rewards, but runaway claims bear scrutiny. At last August’s P&A Leadership Summit, I had the honor of leading a panel of experts in a discussion about anticipating, identifying and properly managing such scenarios.
I was joined by Trish Myers, a senior financial analyst with EFG Companies; Matt Russell, risk manager for AUL Corp.; Jeff Robinson, Alpha Warranty’s vice president of risk and operations; and John Sopocy, vice president of claims and risk management for Vehicle Administrative Services.
Identify the Risk
The term “high-risk” can have a number of different meanings, Sopocy said, so the first step is to identify the type of risk at play. If a dealership has a core customer base that is outside of the usual ratio the company uses to determine risk, for example, that could be skewing the results.
Myers suggested the next step could be to look at how long the service contracts have been active when the claims are initiated, as well as the severity — are they within expectations for that dealership’s vehicle mix and market? If they are consistently steep, “That can be an indication of dealers not prepping the cars for sale,” Myers said, noting dealers can fall into the habit of using claims to pay for reconditioning. She also advises providers to look at earnings and loss ratios — some early warning signs might not be valid, she stressed, so it’s important to gather all the data and take the time to understand what they mean.
This can be a complex process, Russell said, but he agreed it is necessary. “We try to split the data between the statistical side and the behavioral side. It’s important to look at those earnings and loss ratios and other statistical models, but it’s just as critical to look at the behavioral data as well.” He said a review of service-drive records can help determine whether high-risk red flags are just a series of coincidences or a clear pattern.
But just identifying a potential risk isn’t enough. “The first move, after identifying a high-risk dealership, is to have a conversation with them,” said Robinson.
In many cases, the panel agreed, the dealer and their top management team is not aware of how the products are performing. Some are getting incomplete reports from their F&I or service directors; others simply aren’t interested. This can lead to awkward conversations with dealers and dealership personnel, but determining whether a client is “high-risk” is difficult without getting the big picture.
One way to approach the subject is to ask the client to “show the numbers, don’t explain the numbers,” said Russell. He noted that he’ll compartmentalize the data, setting aside, for example, vehicles with extremely high mileage. Then he’ll segment by make and model and even by engine type, if he’s able. “In essence, we’re just trying to show the ‘Why,’” he said, which in turn helps the conversation go more smoothly. The claims administrator then avoids the appearance of leveling accusations. They are simply bringing a business problem to the table and asking, “What can we do to fix this?”
Myers agreed and said this approach is typically well-received. “I’ve never had pushback from the service manager or general manager of the dealership.” She noted that, most of the time, the provider is viewed as a partner, and the dealer wants to get to the bottom of losses and increased claims just as much as the provider does.
Control the Costs
So how can providers keep the cost of high-risk dealerships from spinning out of control? To start, said Sopocy, it’s about stating upfront what is covered — and what isn’t — so everyone is on the same page. He noted that the two biggest cost generators tend to be pre-existing conditions and “upselling,” when the customer brings their vehicle in to address one problem and the service advisor convinces the customer to fix something else.
“On a claim-by-claim basis, it can be really hard to detect that,” Sopocy noted. An individual claim for an oil gasket replacement might appear to be valid on the surface. But if the customer just came in for a standard oil change, and they were then convinced to replace additional parts, it’s a problem.
To combat that, Sopocy advises providers and administrators to have the conversation about expectations as soon as possible. Making sure that the service advisors know that it’s OK if a part is a bit more worn on an older vehicle — that doesn’t mean it has failed or will fail. Replacing it just because they can is a waste of everyone’s time and money. One of the ways they train for this, he noted, is to ask service advisors a simple question: “If this was your car, would you take $500 out of your pocket to replace the part?” In most cases, they say they would not, and that establishes the correct mindset.
The next step is to teach service advisors how to document correctly. Rather than just submitting a claim for an oil gasket, they should note in the paperwork that the customer came in for an oil change and it was noticed that the gasket showed signs of wear.
Russell agreed that getting everyone on the same page is a good first step to controlling costs. With buy-in across the board, a process that will work for everyone can be developed. “It’s about getting everyone on the same page so they know what to expect,” he said.
Robinson agreed, noting, “The dealer needs to understand that it’s a partnership, and that our goals are aligned. … When it’s a healthy book of business, the customer is happy, the service center is happy, the dealership is happy, the administrator is happy — everybody is happy.”
Redemption: Turn High-Risk Clients Into Low-Risk Clients
The panel agreed that, just because you have identified a dealership as high-risk, that doesn’t mean they have to stay that way.
Redemption is possible, Russell said, and it comes in many forms. For new clients, it may just be a matter of patience: It is not uncommon to see a high rate of claims for the first wave of service contracts that flattens out over time. He also noted that, for administrators, it is always worth checking the notes of the claims adjusters. They are on the front lines, and have a much better idea of what is actually going on. Reporting is key, because you have to understand where the problem is if there is any hope of fixing it.
In some cases, Russell pointed out, one make or model can cause the bulk of the issues. At the end of the day, the dealership has to be willing to trust and buy into the administrator’s recommendations. “It’s about trusting us, working with us,” he said.
To get there, said Sopocy, it really is critical to approach them with the numbers — show them their losses today and demonstrate what the projections will be with a different process in place. “If you lay it out, here’s where we are, and, if nothing is done, it stays the same. Here’s where we’re going to be a year or two from now, and it’s normally not a very pretty picture. And then you model it by ‘If we reduce claims, this is what can happen; if we add additional sales, this is what could happen.’ You can show them a couple different ways to get it to a better space.”
If they are a good client, Sopocy added, and they are committed to making it work, the administrator can lay out different strategies — including at least one that doesn’t necessarily include a rate increase — to improve performance across the board and reduce the client’s risk factor.
Russell agreed, adding that it’s important to understand that, in some cases, risk and redemption can’t be had by simply increasing rates. An increase for a given dealership — or even for a given geographic area — can’t be helped because the risk factors just can’t be mitigated any other way. But he stressed that the other solutions should be tried first. If the first time a dealer hears about a problem is when their rate is going up, that doesn’t make for a very profitable partnership on any level.
The agent is another important factor, Russell added. Having a solid relationship with them, and making sure they have all the tools and information they need is important. They can be the provider or administrator’s “boots on the ground,” ready and available to talk to the dealer when a problem first surfaces. “Getting the agent involved is key,” he said. “They’re the ones who hold the relationship.”
Robinson noted that the agent is the first person some dealers call when they have an issue with a claim or anything else. The agent can therefore be helpful in determining whether there is an issue that needs to be solved, with or without the administrator’s help, or whether it’s an isolated incident, a coincidence, or a spike that will level off in time.
Just because a dealership is high-risk, doesn’t mean the provider shouldn’t take a chance — and high-risk today doesn’t necessarily mean high-risk tomorrow. Many dealers will welcome the chance to work with administrators to improve programs and profits, and can end up being some of the most loyal and reliable customers the provider has on the books. It’s all about managing the risk appropriately, setting expectations, and offering the right training to the right people.
More Industry
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →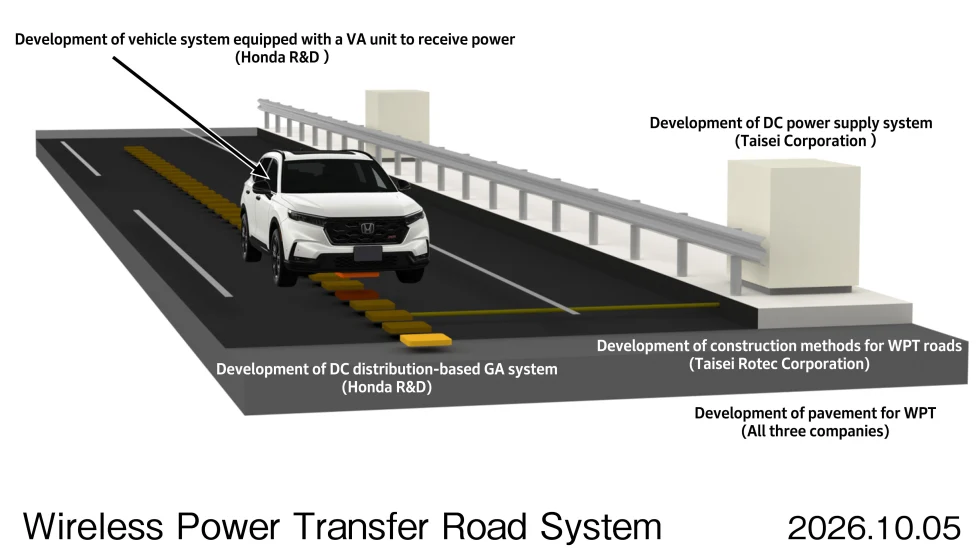
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →