

The Evil that Men Do: Players Who Abuse the System (Part I)

The Evil that Men Do: Players Who Abuse the System (Part I)
The nice thing about vehicle service contracts is that they can generate a lot of money for those who sell them. The bad thing about vehicle service contracts is that they can generate a lot of money for those who sell them.
What I mean by that seeming contradiction is that the same system that can create fair returns for a selling dealership can create unfair returns if a dealer abuses the system. And those unfair returns come out of the revenues and reserves of other players in the service contract food chain.
But the temptation to "game the system" is not limited to unethical dealerships. In fact, virtually everyone involved in the service contract environment can cheat it to their own advantage. Given that everyone who participates needs to play fair for the system to work for all, how can the "bad guys" be controlled?
This article will examine who the players are and how they can cheat the system. Next month we will discuss what can be done about it.
Starting from the top of the food chain and working our way down, the players in the service contract ecosystem include underwriters, administrators, agents, dealerships and consumers. Each has an opportunity to cheat. Anecdotal evidence and actual experience suggest some will, from every segment of the chain.
Underwriters
First are the underwriters. How can they cheat the system? By failing to pay administrators for legitimate claims, for starters. Collecting premiums and not paying claims is not a sustainable business model, but it works great in the short term.
Other ways to harm the system include failure to maintain adequate reserves, failure to follow rational underwriting standards and failure to maintain adequate records. Think all of this is hypothetical? Then recall the case of National Warranty Insurance Risk Retention Group.
In the first half of 2003, National Warranty was found to have committed all of the sins listed above. By summertime, it was in court-ordered liquidation. Its demise left selling dealerships and consumes holding an $83 million bag of unfunded obligations. How could this have been prevented?
The easy answer is not to accept an underwriter with less than an A.M. Best rating of A- (Excellent) or better. But wait - National Warranty had such a rating. In fact, its fall from grace was so rapid as to be worth noting the timeline of its death spiral:
March 10, 2003: A-
March 11, 2003: B++
May 23, 2003: B
June 6, 2003: Joint Provisional Liquidators arrive to examine National Warranty's books June 9, 2003: Liquidation ordered
When underwriters cheat, they generally cannot cheat for long. Their end is assured. The best way to handle bad underwriters is to avoid them in the first place.
Administrators
Administrators can cheat the system in many of the same ways an underwriter can: collect premiums and not pay legitimate claims. Or by creating contracts that suggest great coverage but provide very little (that's called a deceptive trade practice).
The best recent example of this may be the care of LifeLock, the company that markets identity restoration services. (Full disclosure: the author has an interest in a company that competes with LifeLock). LifeLock acts like a third-party administrator - it sells a promise of future service under it's own brand, operates call centers to confirm coverage and pays third parties to perform services for its covered members.
The problem with LifeLock is that its contract contained so many exclusions and limitations that it was difficult to tell what duties it actually had to perform. As Federal Trade Commission Chairman Jon Liebowitz put it, "While LifeLock promised consumers complete protection against all types of identity, in truth, the protection it actually provided left enough holes that you could drive a truck through it."
As a result of this practice, 35 state attorneys general and the FTC sued LifeLock. LifeLock agreed to a settlement under which it was fined $35 million ($23 million suspended if LifeLock cleans up its act) and promised to sin no more.
Agents
Most administrators market their wares through an independent agent base. Such agents are their eyes and ears on the ground, and are usually in the best position to prevent problems from arising in the first place.
Agents can cheat the system by, for example, signing business the agent knows has experienced unusually high loss ratios. Or by withholding cancellation/reimbursement checks from dealerships (hey, it happens).
But perhaps the worst impact agents can have on the service contract system is by what they fail to do: properly educate dealership personnel on the features, benefits and purpose of a service contract program. Failing in this duty can result in high losses, bad relationships, and cancelled business. Oh, and lawsuits.
True story: one dealership sold GAP to an unusually high percentage of its financed deals. Furthermore, many of those deals were "over-financed," meaning the amount financed was often in the 150 percent to 160 percent over MSRP/NADA value range. And the GAP policy the dealership sold had a limit of 125 percent over MSRP/NADA value.
Under such circumstances, many GAP claims were certain to fall short of the actual loss suffered by the customs who had bought GAP. They did, and two class action lawsuits were filed against the dealership.
Now comes the interesting part. The dealership threatened to sue the F&I agent and the administrator for failure to properly train its personnel on the limitations contained in the GAP contract.
That case resolved in the agent's and administrator's favor, but the point is clear: an agent's failure to properly train dealership personnel, and prove that it did so, can result in liability for both the agent and the administrator.
Dealership
How can a dealership cheat a service contract program? Let me count the ways. It can pack payments to include a service contract it doesn't deliver and keep the entire premium. It can call in false claims. It can intentionally sell a service contract to a customer with an expensive pre-existing condition. It can use the service contract as a menu of things to look for when a vehicle is on the lift. It can fail to remit payments to the administrator. It can fail to forward cancellation checks to customers (hey, it happens).
The most common sin committed by dealerships in the realm of service contracts is broadly operating as if the program were its own private piggy bank. While this is unethical, unfair, possibly illegal and a drain on any reinsurance or participation program, for a dealership struggling to keep the lights on (or just plain greedy), it is tempting to view the service contract program as a convenient ATM.
Customers
And finally, there is the Little Guy. What can an individual customer do to cheat the system? Truth be told, very little - unless he is aided and abetted by a cooperative service writer or other dealership employee.
For example, a customer with a bad transmission might purchase a power train contract, wait 30 days (or less if the dealership employee will back-date the application) and have the work done under the contract. Foul!
It could be that the only self-serve fraud an individual customer can perform without dealership help is arranging for a car to be stolen in order to file a GAP claim (hey, it happens).
The foregoing is just an overview of ways to chisel a dishonest portion from the service contract pie. A full catalogue of dishonesty is probably impossible to record. Next month: what to do about it.
More Industry
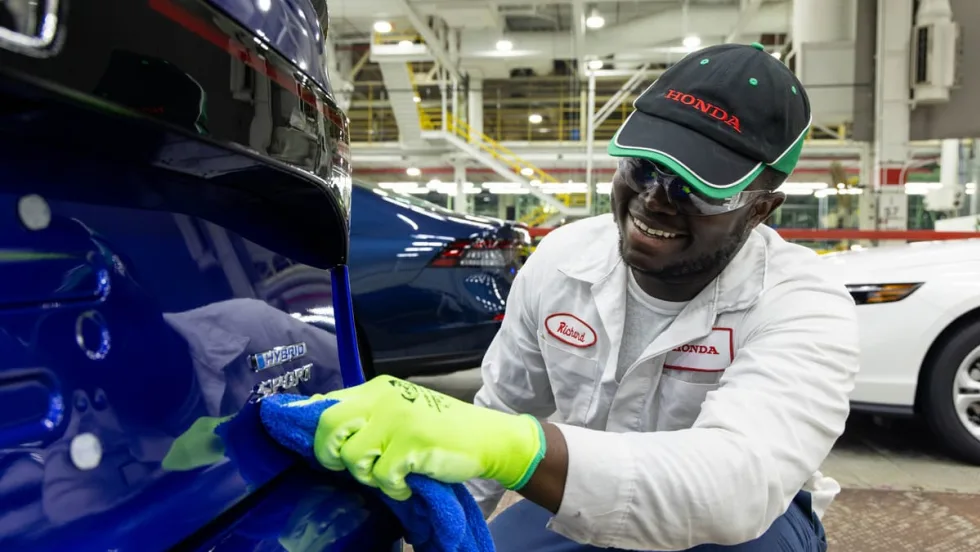
Honda Embraces Hybrid Fever
The automaker plans a new Ohio factory, along with investments in existing U.S. and Canadian plants, to significantly boost hybrid production here.
Read More →
Dealerships Must Show Up Where It Matters
How car buyers find your dealership has fundamentally changed. New evidence reveals the importance of your presence on social media, Google search, and large language models.
Read More →
CPO Sales Could Take Off in the Right Conditions
A recent Cox Automotive consumer survey reveals the size of an undertapped market for the vehicle segment given affordability pressures.
Read More →
Global Consumer Trends Diverge
Price remains a top consideration for U.S. car buyers, and they are the most brand-loyal consumers to established automakers, according to a new survey.
Read More →
Badger State Dealership Gets New Owner
The longtime southern Wisconsin store moved from one area auto group to another, keeping the business in Dairyland.
Read More →
The Cycle of Negative Equity
Third-quarter data shows consumers still rolling over debt and stretching loan terms, raising their risk of remaining underwater.
Read More →
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →