

BB&T Switches Back to Markups as CFPB Shifts Away From Enforcement

GREENSBORO, N.C. — Nearly three years after switching to a flat-fee compensation model in response to the Consumer Financial Protection Bureau (CFPB)’s targeting of dealer participation, BB&T Dealer Financial Services announced to its dealers it will officially return to a dealer spread compensation plan on March 14.
The decision, detailed in a Feb. 7 dealer bulletin obtained by F&I and Showroom, was announced about a week after Acting CFPB Director Mick Mulvaney stripped the bureau’s Office of Supervision, Enforcement and Fair Lending of its enforcement powers — the same division that imposed millions of dollars in fines on auto finance sources for alleged discriminatory interest rate markups.
“While we had some success with the flat fee program announced in 2015, BB&T also experienced an overall reduction in volume,” said BB&T spokesperson Brian Davis. “So to provide our dealer clients with more options and better flexibility, we will introduce a more traditional auto pricing program in mid-March.”
The bank’s new compensation plan allows for a rate markup of up to 2%, with spread compensation paid at an 80/20 split, according to the finance source’s dealer bulletin. Contracts purchased at retention will be paid a flat on terms greater than 47 months and amounts exceeding $7,500. The bank noted in its bulletin that the changes “will allow us to offer lower rates to you and your consumer clients.”
BB&T became one of two finance sources to employ a flat-fee compensation model when it made the switch on July 1, 2015. The other was BMO Harris, which made the switch in April 2014 — about a year after the bureau issued its controversial guidance on dealer participation and about four months after the regulator joined the Department of Justice in ordering Ally Financial Inc. and Ally Bank to pay $98 million in damages and fines as part of the largest auto loan discriminatory settlement in history.
At the center of that settlement was the bureau’s five-page fair lending guidance, in which the CFPB said it would hold lenders active in the indirect auto finance channel liable for unlawful, discriminatory pricing. It alleged that bank policies which allow dealers to mark up interest rates on retail installment sale transactions as compensation for services rendered create a significant risk of unintentional, disparate impact discrimination.
The bulletin listed a variety of steps finance sources could take to address the bureau’s fair lending concerns, including moving to flat fees. That guidance, however, is now in question.
In early December, the Government Accountability Office said the bureau’s March 2013 guidance on dealer participation falls under the Congressional Review Act and should have been submitted to Congress and the Comptroller General of review before it took effect. Legal experts say the GOA’s finding gives Mulvaney, who was appointed acting director by President Trump on Nov. 24, the authority to rescind the bureau’s guidance.
The acting director has yet to act on that authority. However, Mulvaney’s decision to remove the fair lending division’s enforcement powers does defang an office that has headed up some of the bureau’s most high-profile cases. In a memo sent to staffers announcing the move, Mulvaney said division staffers will now be focused on “advocacy, coordination and education.”
Since his appointment, Mulvaney has also called for a review of the payday lending rules the bureau finalized last year, called off a four-year investigation into a South Carolina-based subprime lender, dropped a lawsuit against a four online payday lenders, and initiated a series of Requests for Information as part of an examination of the bureau’s policies and practices.
On Monday, Mulvaney released the bureau’s five-year strategic plan. The 16-page document — condensed from the 40-page plan issued under former CFPB Director Richard Cordray in April 2013 — seemed to confirm a shift away from enforcement. In a press release announcing the plan, the bureau explained it “will now focus on equally protecting the legal rights of all, including those regulated by the bureau, and will engage in rulemaking where appropriate.”
“If there is one way to summarize the strategic changes occurring at the bureau, it is this: we have committed to fulfilling the bureau’s statutory responsibilities, but go no further,” Mulvaney wrote in the plan’s preface. “Indeed, this should be an ironclad promise for any federal agency; pushing the envelope in pursuit of other objectives ignores the will of the American people … Pushing the envelope also risks trampling upon the liberties of our citizens, or interfering with the sovereignty or autonomy of the states or Indian tribes. I have resolved that this will not happen at the Bureau.”
Summarized in the report’s appendix are “key evaluation efforts” the bureau has undertaken under Mulvaney’s watch, including its Requests for Information. Listed are three goals, the second of which details “efforts to improve the supervision examination and enforcement activities” of the bureau’s Supervision, Examination and Fair Lending Division. One of those efforts includes piloting a project for conducting supervisory activities “to supplement the traditional examination process.”
BB&T officials did not say whether the changes taking place at the CFPB motivated its decision to end the finance source’s flat-fee compensation program, although its dealer bulletin does note that it “remains firmly committed … to the fair and equal treatment of all consumers.” Then there’s the bank’s fourth-quarter earnings call on Jan. 18, when officials told investors that the bank, which operates in 15 states, plans to take it auto business “more nationally.” They added that the opportunity to expand lies in the nearprime credit spectrum.
“The CFPB came in with an iron club and made us change the way we priced our product through our indirect auto purchasing through auto dealerships and that caused the substantial runoff in that business,” King said. “And because the market itself was getting unprofitable, because the structure that we went to based on CFPB guidance, both of those combined drove the volume down in auto.
“We believe we’re going to be very soon moving back to a more traditional auto pricing program like we had before,” he added. “That will increase that volume in the auto portfolio and the spreads will remain good.”
More Industry
Badger State Dealership Gets New Owner
The longtime southern Wisconsin store moved from one area auto group to another, keeping the business in Dairyland.
Read More →
The Cycle of Negative Equity
Third-quarter data shows consumers still rolling over debt and stretching loan terms, raising their risk of remaining underwater.
Read More →
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →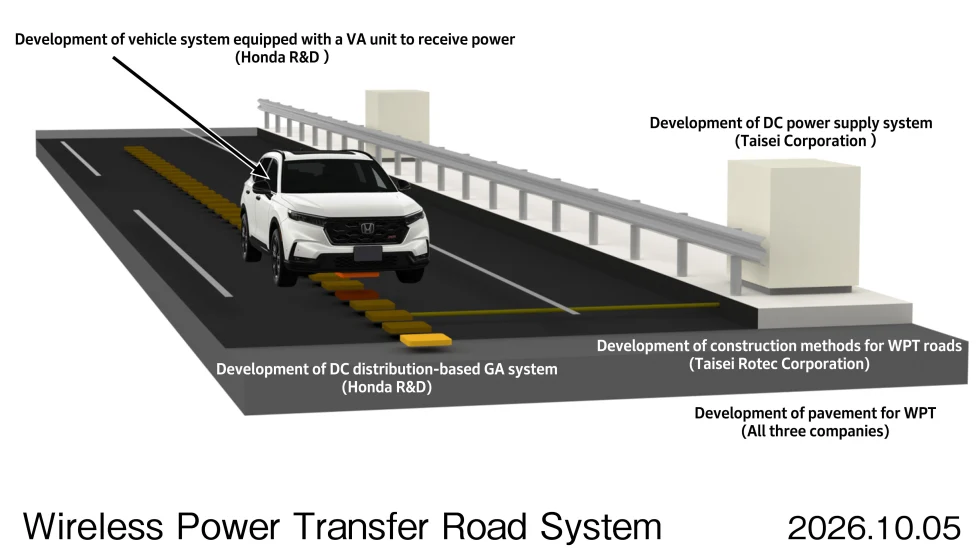
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →