House Approves Resolution to Repeal CFPB's Dealer Participation Guidance

WASHINGTON, D.C. — The U.S House approved on Tuesday its version of the resolution of disapproval of the Consumer Financial Protection Bureau’s dealer participation guidance. The resolution now heads to President Trump’s desk, where it is expected to be signed.
The 234-175 vote was cast largely along party lines, although 11 Democrats crossed the aisle to approve the resolution. One Republican, Ileana Ros-Lehtinen of Florida, voted against the resolution, which, when signed by President Trump, will bring an end to the automotive retail and finance industry's five-year effort to get the bureau’s controversial March 2013 guidance rescinded.
“This vote indicates that American consumers have spoken to their elected representatives to say they want competitive pricing on vehicle loans,” said Chris Stinebert, president and CEO of the American Financial Services Association, in a statement issued by the lender trade group. “We are an industry that competes for consumers’ trust as well as their business while helping them acquire vehicles that support their transportation needs.”
The vote comes less than a month after the U.S. Senate voted 51-47 to approve its version of the resolution and five months after the Government Accountability Office (GAO) said Congress has the power under the Congressional Review Act (CRA) to repeal the bureau’s dealer participation guidance.
Under the CRA, both houses must approve resolutions of disapproval by a simple majority and receive the president’s signature to kill a regulation. When the latter happens to S.J. Res. 57, which was introduced in March by Sen. Jerry Moran (R-Kansas), it’ll mark the first time the CRA has been used on a rule that has been in effect for several years. And once repealed, the CRA prohibits the reissuance of a rule in substantially the same form unless authorized by Congress.
The CFPB alleged in its five-page fair lending guidance that bank policies which allow auto dealers to mark up interest rates on retail installment sale transactions as compensation for services rendered create a significant risk of unintentional, disparate impact discrimination. It also warned lenders active in the indirect auto finance channel that they would be held liable for unlawful, discriminatory markups.
The bulletin goes on to state that lenders operating in the indirect auto finance channel “should take steps to ensure that they are operating in compliance with the [Equal Credit Opportunity Act] and Regulation B as applied to dealer markup and compensation policies.” It then listed a variety of steps and tools they could employ to address the bureau’s stated fair lending risks, including “eliminating dealer discretion to markup buy rates and fairly compensate dealers using another mechanism, such as a flat fee per transaction, that does not result in discrimination.”
Auto industry trade groups have argued that the bureau used its guidance to indirectly regulate the activities of dealers, which are mostly exempt from the bureau’s oversight under the Dodd-Frank Act. They also claimed the bureau was aware its methodology for determining disparate impact and potential harm to protected classes was flawed and prone to overestimation, yet pushed forward with claims of discrimination that resulted in enforcement actions that imposed millions of dollars in fines on auto finance sources, including Ally Financial.
The guidance also caused several finance sources, including BB&T and BMO Harris, to switch to a flat-fee compensation model. BB&T switched back to a dealer spread compensation plan earlier this year, while BMO switched to a three-tiered flat-rate model last summer.
The guidance was also behind consent orders the CFPB entered into with Fifth Third Bank, Toyota Motor Credit Corp., and American Honda Finance Corp regarding their dealer markup policies. As a result of those orders, the bank and two captives agreed to lower their markup caps to 1.25% and 1%. Fifth Third’s consent order, however, is set to expire this September, while Toyota Motor Credit’s and Honda Finance’s consent orders are set to expire in February 2019 and July 2020, respectively. The three finance sources yet to say whether they’ll return to a dealer participation model when they do.
“There's no question that this is a rule masquerading as guidance. The CFPB never submitted the guidance to the GAO. They could have done so. Had they done so the 60-day clock would have run, we wouldn't be here,” David Regan, executive vice president of legislative affairs for the National Automobile Dealers Association (NADA), said last week during a press briefing. “They chose not to submit that to Congress because they did not want the additional exposure to public notice and comment. Within just a few weeks of the guidance being issued in March of 2013, the congressional inquiries started pouring in asking very specific questions about the methodology that we now know was flawed. And yet, the agency repeatedly refused to respond to these questions.”
Congress has attempted to kill the bureau’s guidance through the legislative route. In November 2015, the House of Representatives approved the Reforming CFPB Indirect Auto Finance Guidance Act by a 332-96 vote. The bill, however, was not acted upon by the Senate before the end of the 114th Congress.
Last March, Sen. Toomey asked the GAO whether the CFPB’s guidance on dealer participation falls under the CRA. The agency delivered its answer this past December, writing in a letter to Toomey that it did.
When it initially issued its guidance, the bureau argued that because it had no legal effect on regulated entities, the CRA does not apply. The GAO, however, stated in its response to Toomey’s request that the bulletin “fits squarely within the Supreme Court’s definition of a statement of policy,” because it provides information on the manner in which the bureau planned to exercise its discretionary enforcement power.
And according to the GAO, the CRA “establishes special expedited procedures under which Congress may pass a joint resolution of disapproval that, if enacted into law, overturns the rule.” In a statement posted on its website just after the GAO delivered its answer, Sen. Toomey said he intended “to do everything in my power” to repeal the bureau’s guidance under the CRA.
“The joint resolution is a measured response to the CFPB’s attempt to avoid congressional scrutiny by issuing ‘guidance’ that imposed a new policy without necessary procedural safeguards,” said Peter Welch, president and CEO of the NADA, in a statement issued following the House vote. “Enactment of S.J.Res. 57 will help ensure every consumer’s right to get a discounted loan in the showroom.
“Every customer deserves to be treated honestly and fairly when purchasing or financing a car or truck, and there is no room for discrimination of any kind, period,” he continued. “We continue to encourage all local dealerships to take up NADA’s voluntary fair credit compliance program, which is based on a U.S. Department of Justice model. It helps eliminate fair credit risk in auto lending while ensuring a competitive marketplace.”
More Industry
Charger Network Growth Slows
Despite a projected increase in public EV chargers in 2026, charging infrastructure remains a top concern for consumers as the gap between the most and least EV-friendly places remains substantial.
Read More →
Lenders, Consumers Take on More Auto Loan Risk
September records loosened credit access the most in over a decade as buyers took advantage of the conditions to afford trading, though loan applications fell.
Read More →
Next-Gen Hybrids in Sight
Dealerships can expect to see revamped hybrids from Honda next year as the company rolls out a new system and model lineup.
Read More →
Gem State Stores Change Hands
A larger auto group founded in the industry’s early years sold two franchises to a neighbor group that's on a growth spurt.
Read More →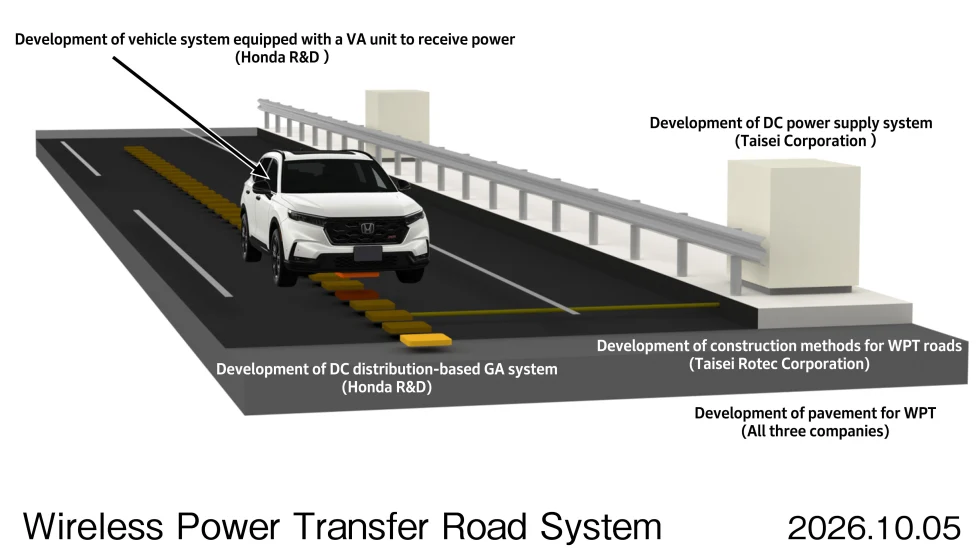
Charging In Motion
Honda has been researching wireless in-motion charging for electric vehicles since 2025, and new technology developments have put it a step closer to a final product.
Read More →
Twin Cities Stores Sell
Minnesota-based Walser Automotive Group made what it called the most significant acquisition in its history with a three-rooftop deal in Minneapolis.
Read More →
U.S. Auto Sales Still Below Prepandemic Levels
Mobility Global industry observers don’t expect the market to return to the higher volumes that became routine before Covid but to stay well below its potential.
Read More →
The Powertrain Shift
Electric-vehicle owners are backpedaling, according to new data, with product availability driving many to shift back to gas-powered engines.
Read More →
Achromatic Autos
The shades that dominate the U.S. car market don’t call attention to themselves, though grayscale may have plateaued after a 30-year upswing, research shows.
Read More →
Used-Vehicle Affordability Worsens
Listing prices in August defied seasonal trends, rising above $27,000 for the second time this year.
Read More →